One of the most common questions business owners ask when considering financial leadership is:
How big does my company need to be before hiring a fractional CFO?
It is tempting to answer that question with a specific revenue number.
But revenue alone rarely determines whether a business needs CFO-level financial leadership.
A $5 million company with predictable revenue, strong margins, simple operations, and stable cash flow may have relatively straightforward financial needs.
Another $5 million company may operate multiple locations, carry significant inventory, employ dozens of people, experience rapid growth, and constantly struggle to predict cash.
Same revenue.
Completely different financial complexity.
That is why the better question isn’t simply how much revenue your business has.
It is whether the financial complexity of your business has outgrown the financial support you currently have.
Is There a Revenue Threshold for Hiring a Fractional CFO?
There is no universal revenue threshold.
However, fractional CFO services often become increasingly valuable once a business reaches several million dollars in annual revenue and financial decisions begin carrying larger consequences.
At CFO For Hire, our fractional CFO services are generally designed for growing businesses with approximately $2 million to $100 million in annual revenue.
But those numbers should be viewed as a range rather than a rule.
Some businesses may benefit from CFO-level guidance earlier.
Others may operate successfully for considerably longer with a strong controller, CPA, and accounting team.
The deciding factor is usually complexity.
Why Revenue Isn’t Enough to Determine Whether You Need a CFO
Imagine two companies generating $10 million in annual revenue.
Company A has:
- One location
- Predictable recurring revenue
- Limited inventory
- Stable margins
- Few employees
- Strong cash flow
Company B has:
- Five locations
- Significant inventory
- Rapid hiring
- Seasonal revenue
- Multiple sales channels
- Changing gross margins
- Tight working capital
Company B clearly has more financial complexity even though both companies generate identical revenue.
The question therefore becomes:
How difficult has the business become to financially manage?
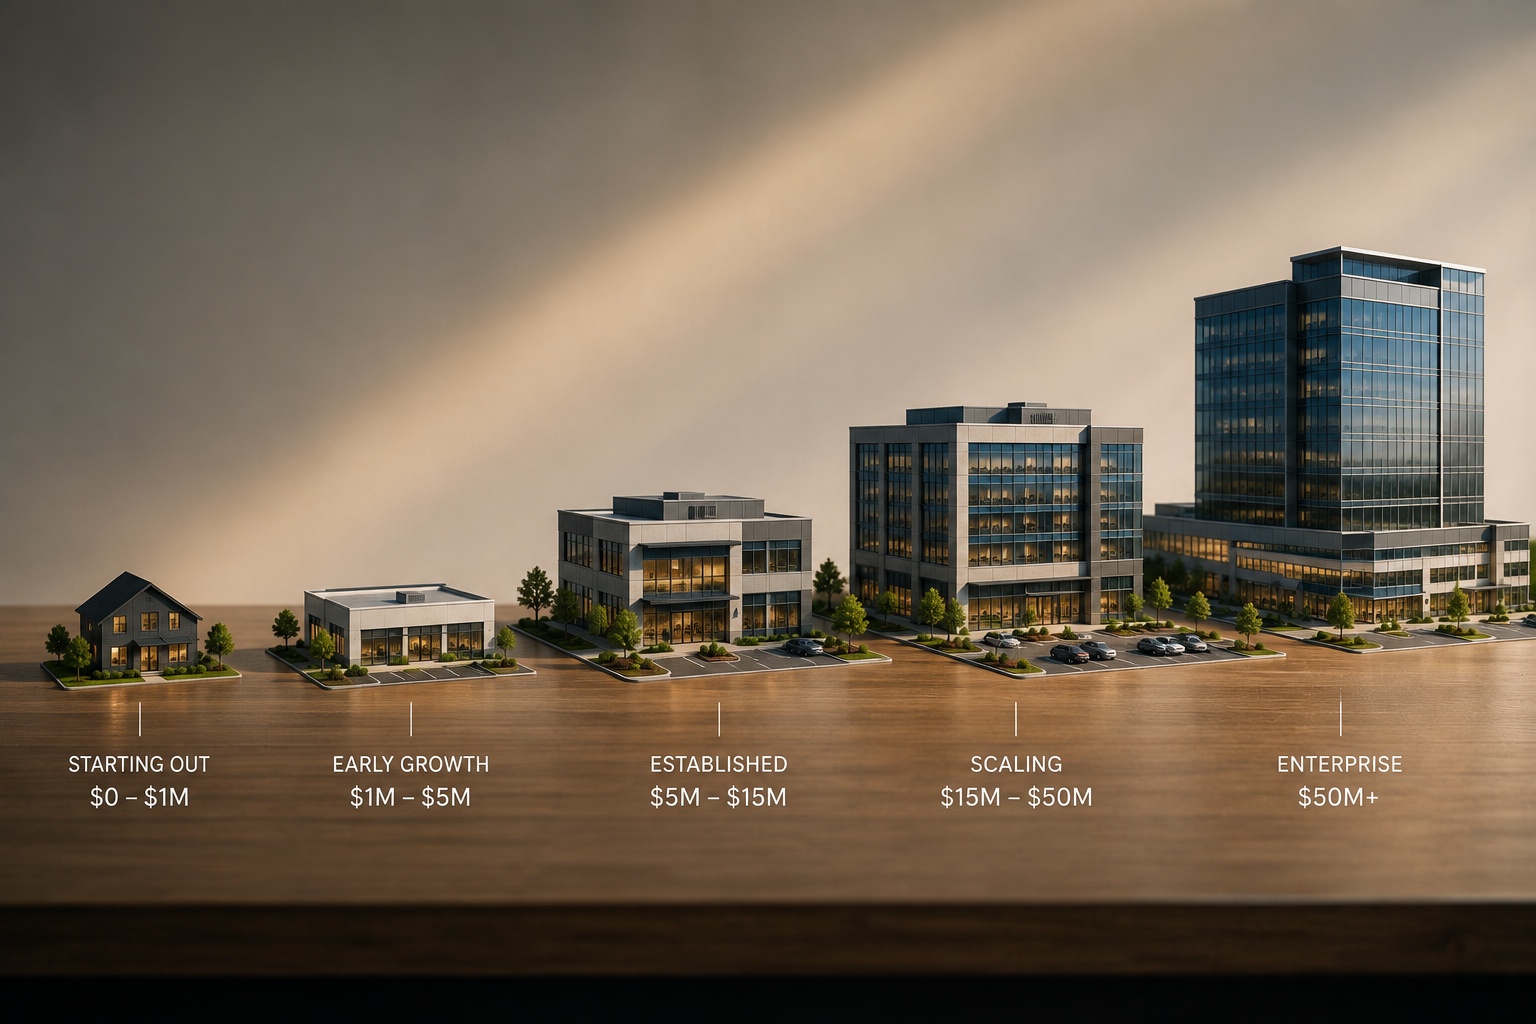
The $1 Million to $3 Million Stage
At this stage, many businesses can operate successfully without a fractional CFO.
A capable bookkeeper, CPA, and owner may be sufficient if the business is relatively simple.
The owner often remains heavily involved in financial decisions.
But there are exceptions.
A smaller company experiencing rapid growth, raising capital, acquiring another business, or dealing with severe cash-flow problems may benefit from CFO-level guidance much earlier.
The key isn’t simply company size.
It is the financial consequences of the decisions being made.
The $3 Million to $10 Million Stage
This is where the need often begins changing.
The company may now have:
- More employees
- Larger payroll
- More customers
- Higher inventory
- Additional locations
- More complicated pricing
- Larger vendor commitments
- Increased working-capital requirements
At this point, financial statements alone may no longer provide enough information.
Management begins asking questions such as:
Can we afford another hire?
How much cash will growth require?
Why are margins changing?
Which customers are most profitable?
Should we open another location?
What happens if revenue slows?
Those aren’t bookkeeping questions.
They are CFO questions.
The $10 Million to $25 Million Stage
Once a business reaches this size, the financial consequences of poor decisions become considerably larger.
A one-percentage-point margin problem in a $2 million company represents $20,000.
At $20 million, that same percentage point represents $200,000.
Small financial improvements become valuable.
Small financial mistakes become expensive.
Management may need:
- Rolling financial forecasts
- Detailed cash-flow forecasting
- Department or location profitability
- KPI dashboards
- Working-capital management
- Scenario modeling
- Capital planning
- Budget accountability
This is often where fractional CFO services can create significant leverage.
The business may clearly need CFO-level thinking while still not requiring a full-time CFO every day.
The $25 Million to $50 Million Stage
At this level, the question often changes.
Instead of asking:
Do we need a CFO?
Management may begin asking:
Do we still need a fractional CFO, or is it time for a full-time CFO?
That depends on organizational complexity.
A $30 million company may have a strong controller and accounting team handling daily financial operations while using a fractional CFO for strategic financial leadership.
Another $30 million business may have acquisitions, outside investors, complex financing, multiple entities, or substantial operational complexity that requires a full-time executive.
The $50 Million+ Stage
As businesses become larger, the likelihood of eventually needing a full-time CFO increases.
But revenue still doesn’t make the decision automatically.
Some organizations remain relatively straightforward.
Others become highly complex much earlier.
The relevant questions include:
How large is the finance team?
How frequently are major financial decisions being made?
Does the CFO need to manage employees every day?
Are there investors or a board?
Is the company pursuing acquisitions?
How complex is financing?
How many locations, entities, or business units exist?
The greater the complexity, the stronger the case for full-time financial leadership.
Five Signs Revenue Has Become Less Important Than Complexity
Regardless of company size, there are several signals that CFO-level support may be needed.
1. You Are Profitable but Cash Is Constantly Tight
This is one of the clearest warning signs.
Growth can consume cash through inventory, accounts receivable, hiring, capital expenditures, and other working-capital requirements.
A profitable company can therefore experience serious liquidity problems.
2. You Cannot Reliably Forecast the Next 6 to 12 Months
A budget created once a year isn’t enough for many growing businesses.
Management should understand how changes in revenue, margins, payroll, and operating expenses affect future profitability and cash.
If every major decision requires guessing what the business can afford, forecasting has probably become inadequate.
3. Financial Reports Tell You What Happened but Not What to Do
Historical financial statements are essential.
But they are only the starting point.
As businesses grow, owners increasingly need interpretation.
Why did margins decline?
Why did cash fall?
Which locations are performing?
What happens if we hire?
What should management change?
4. Decisions Are Becoming More Expensive
Early in a company’s life, a poor decision may cost several thousand dollars.
Later, decisions involving hiring, pricing, inventory, expansion, financing, and capital investment can involve hundreds of thousands or millions of dollars.
At that point, the economics of better financial decision-making change dramatically.
Paying for experienced financial analysis becomes easier to justify when the decisions being analyzed become materially larger.
5. The Owner Has Become the De Facto CFO
This is common.
The business grows.
The accounting team handles the books.
The CPA handles taxes.
But when someone needs to decide whether the company can afford a major investment, everyone turns to the owner.
The owner becomes the CFO by default.
The problem is that the owner is also running the company.
A fractional CFO can take ownership of the financial analysis surrounding those decisions while allowing the owner to remain focused on operating and growing the business.
Bookkeeper, Controller or Fractional CFO?
Another way to determine whether your company is ready is to evaluate what financial capability is actually missing.
A bookkeeper primarily ensures transactions are recorded.
A controller generally ensures the accounting process and financial statements are accurate.
A CFO focuses on what happens next.
That includes:
- Forecasting
- Cash strategy
- Profitability
- Capital allocation
- Financial modeling
- Risk
- Strategic decision support
Many businesses don’t need to replace their existing accounting team.
They need to add the missing financial leadership layer above it.
How Much Should the Business Be Making Before the Cost Makes Sense?
This is where revenue becomes relevant again.
The financial benefit created by the CFO needs to justify the cost.
As a business grows, relatively small improvements can create meaningful financial value.
Consider a $10 million business.
A 1% improvement in gross margin equals $100,000.
At $25 million, it equals $250,000.
At $50 million, it equals $500,000.
That doesn’t mean a fractional CFO will automatically produce a one-point margin improvement.
It demonstrates why better financial management becomes increasingly valuable as a business grows.
The potential financial impact scales with the company.
Don’t Wait for a Revenue Number to Tell You What the Business Already Is
There is a risk in waiting for the company to reach some arbitrary revenue milestone before improving financial leadership.
The need for a CFO often appears before the title does.
If your company is growing quickly, struggling with cash, experiencing margin pressure, making large investments, or operating without reliable forecasts, the financial complexity may already justify CFO-level support.
The Bottom Line
There is no magic revenue number at which every business should hire a fractional CFO.
For many growing businesses, the need begins emerging somewhere in the several-million-dollar revenue range and increases as financial complexity grows.
But revenue should never be the only test.
Look instead at:
Complexity.
Cash flow.
Growth.
Decision size.
Forecasting needs.
Financial visibility.
And the amount of risk management is being asked to handle without experienced financial leadership.
A business doesn’t need a fractional CFO because it crossed a particular revenue threshold.
It needs one when the financial consequences of its decisions have become too significant to manage without CFO-level insight.
[…] Cheaper CFO. There is no single revenue number that determines when CFO support becomes necessary. How much revenue a business should have before hiring a fractional CFO depends more on financial com… If you’re considering fractional CFO services, understanding the onboarding process can help […]
[…] As a company grows, owners often wonder whether they have reached the size where CFO-level support makes financial sense. Revenue can be a useful benchmark for determining when it may be time to hire a fractional CFO, but … […]
[…] Waiting for the business to reach an arbitrary size can create problems of its own. Understanding how revenue and financial complexity affect when to hire a fractional CFO can help own… […]